
Insurance roof replacement in Massachusetts is a full roof replacement paid for, in whole or in part, through a homeowners or commercial insurance claim, typically after wind, hail, or fallen-tree damage that a policy covers as a specific, datable event rather than gradual wear. In Massachusetts, this most often follows a nor’easter that’s torn off shingles or toppled a tree, though hail damage repair claims do come up after severe summer thunderstorms, particularly across inland communities like Waltham and Belmont. Insurance claim roofing has its own process alongside the physical replacement itself: documenting the damage clearly, understanding what your policy actually covers, and, where needed, working through a disagreement between the insurance company’s initial estimate and the actual scope of repair needed. RB Farina Roofing Co has spent more than 10 years replacing storm-damaged roofs throughout Massachusetts and documenting that damage in a way that supports the insurance claims process.
Insurance roof replacement is the process of replacing a damaged roof where some or all of the cost is covered by a homeowners or commercial insurance policy, rather than paid entirely out of pocket. This differs from a standard roof replacement mainly in the documentation and approval process involved: an insurance-covered replacement requires clear evidence connecting the damage to a specific covered event, an adjuster’s review and approval of the claim, and often direct communication between the contractor and the insurance company about the scope of work needed.
Massachusetts homeowners most commonly pursue insurance roof replacement after nor’easter wind damage or fallen-tree impact, both common throughout tree-lined suburban neighborhoods in Arlington, Winchester, and Belmont, and less frequently after hail damage from severe summer thunderstorms, more common inland around Waltham and Lexington than along the immediate coast. Older housing stock throughout Boston, Cambridge, and Somerville also sees insurance claims tied to ice dam water damage, though coverage for this specific cause varies more by policy than storm-wind or hail claims typically do.
Insurance roof replacement applies across residential, historic, and commercial buildings throughout Massachusetts, though commercial claims, common on flat-roofed buildings throughout Waltham and Cambridge, often involve different policy structures and larger claim amounts than a typical residential homeowners policy.

Nor’easters bring sustained wind frequently in the 40-50 mph range with higher gusts, capable of tearing off enough shingle area that a full slope, or sometimes the entire roof, needs replacement rather than a patch repair. This is the most common driver of insurance roof replacement claims in Massachusetts, and it’s most frequent on older roofs throughout Arlington, Winchester, and Belmont, where existing wear combines with storm wind to cause more extensive damage than a newer roof might sustain in the same event. Documenting the specific storm date and the extent of wind damage across the full roof, not just the most visible section, matters for getting an accurate claim approved.
Hail damage repair and replacement claims are a real, though comparatively less frequent, category of Massachusetts insurance work, tied to severe summer thunderstorms, typically between June and August, that produce hail capable of bruising and cracking asphalt shingles. Because hail damage often isn’t visible from the ground, granule loss and shingle bruising show up mainly on close inspection, insurance claims for hail can be more contested than wind damage claims, where torn-off shingles are obvious. A thorough inspection with photo documentation of bruising patterns across the roof is particularly important for supporting a hail-related claim. For more detail on how hail affects Massachusetts roofs, see our hail damage guide.
When storm or hail damage affects only part of a roof, a single slope or section, insurers and contractors sometimes disagree about whether a partial repair using new shingles alongside existing, weathered ones is an acceptable outcome, since new shingles rarely match older ones in color and wear pattern exactly. Massachusetts insurance regulation has addressed this kind of matching concern in general guidance to insurers, and it’s a common point of negotiation on a claim where the damaged section is smaller than the full roof. Documenting the age and appearance of the existing roof alongside the storm damage itself helps support a claim that a full replacement, rather than a mismatched partial repair, is the appropriate outcome.
A fallen tree or large limb can cause damage extensive enough to require full roof replacement rather than a repair, particularly when structural elements like rafters or decking are affected alongside the roofing material itself, a common scenario throughout tree-covered neighborhoods in Arlington, Winchester, and Belmont during high-wind nor’easters. These claims typically involve both the roofing replacement and separate documentation of structural repair needs, and thorough photo documentation of the tree or limb’s position and the resulting damage matters for supporting the full scope of the claim.
Some signs suggest a covered event has caused damage extensive enough to justify an insurance replacement claim rather than an out-of-pocket repair.
Storm and wind signs include a large area of missing, cracked, or lifted shingles after a nor’easter, visible sagging or structural movement following high wind, and any section of roof torn away during a storm.
Hail signs include widespread bruising or granule loss across multiple roof sections, cracked or chipped shingle tabs, and dented gutters, flashing, or vent caps suggesting hail large enough to also affect the roofing material.
Tree and debris signs include a fallen tree or large limb in contact with the roof, punctured decking, and any visible structural damage beyond the roofing surface itself.
Documentation-readiness signs include damage that’s clearly tied to a specific, datable storm event, and a roof condition and age that support a claim for full replacement rather than partial repair.
Call promptly after any storm event causing this kind of damage, since most insurance policies have reporting deadlines, and delayed documentation can weaken a claim even when the damage itself is clearly storm-related.
Step 1: Initial Inspection and Documentation. We conduct a full roof inspection following storm or hail damage, documenting the condition with detailed photos covering the full roof, not just the most visibly damaged section. This typically takes 45-60 minutes.
Step 2: Written Damage Report. We provide a written report and itemized estimate describing the damage, its likely cause, and the scope of work needed, which you can submit as part of your insurance claim.
Step 3: Adjuster Coordination. We can meet with your insurance adjuster on-site to walk through the documented damage directly, helping ensure the full scope, including matching concerns on partial damage, is considered as part of the claim review.
Step 4: Scope and Estimate Review. If the insurance company’s initial estimate doesn’t reflect the full scope of damage we’ve documented, we can provide additional documentation to support a supplement request, though the final coverage decision rests with your insurance company.
Step 5: Material Selection and Scheduling. Once coverage is confirmed, we help select materials appropriate for Massachusetts weather exposure and schedule the replacement.
Step 6: Replacement Installation. The roof replacement is completed using standard installation methods suited to Massachusetts conditions, including proper ice barrier, flashing, and ventilation regardless of the insurance process behind the project.
Step 7: Final Documentation. We provide final photos and documentation of the completed replacement, along with a workmanship warranty, useful for your records. Most replacements are completed within 1-3 days for a standard residential roof once the claim and materials are confirmed.
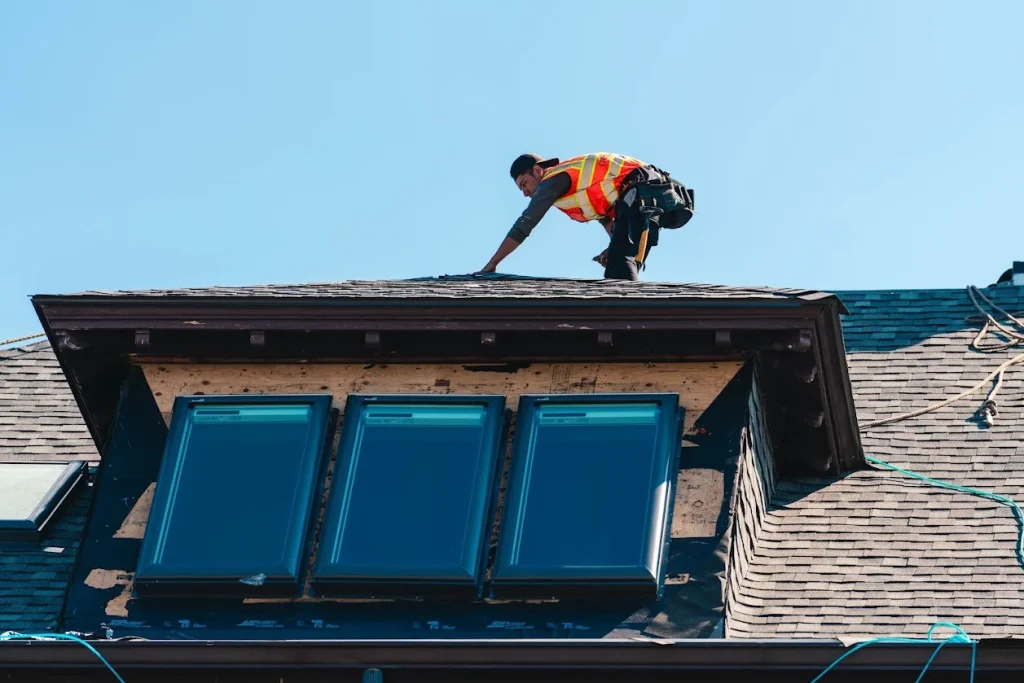
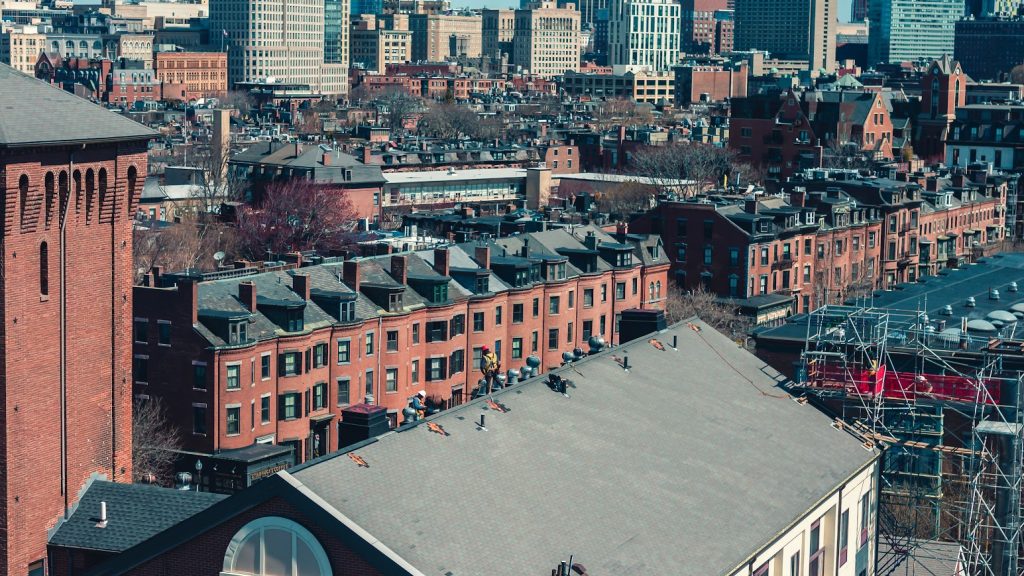
Full Roof Replacement Claims — Used when storm, hail, or tree damage affects the majority of the roof, or when matching concerns make a full replacement the more appropriate outcome for damage limited to part of the roof.
Partial Slope Replacement — Used when damage is clearly isolated to one roof slope or section and matching materials are reasonably available, though this is less common than full replacement on older Massachusetts roofs where exact shingle matches are harder to find.
Supplement Claims — Used when an initial insurance estimate underestimates the actual scope of damage or repair cost, supported by additional documentation and, where useful, direct adjuster communication.
Code Upgrade Documentation — Addresses situations where current Massachusetts building code, such as ice barrier or ventilation requirements, wasn’t part of the original roof and needs to be included in the replacement scope, which some policies cover under ordinance or law provisions.
Denied Claim Documentation Support — Provides additional photo documentation and a written scope of work property owners can use if an initial claim is denied and they choose to appeal or seek further review, though we aren’t a substitute for legal or insurance advice on the appeal itself.
Photograph your roof periodically as a baseline record, ideally each fall, so you have clear documentation of its condition before any storm damage occurs. Schedule a roof inspection promptly after any nor’easter, severe thunderstorm, or high-wind event, even if damage isn’t obvious from the ground, since hail bruising and wind damage aren’t always visible without a close look. Report storm damage to your insurance company as soon as possible after discovering it, since most policies have reporting deadlines that can affect claim eligibility. Keep records of any prior roof repairs or replacements, which can help establish the roof’s condition before a specific storm event. Address minor damage promptly rather than waiting, since delayed repair can sometimes complicate a claim by making it harder to distinguish storm damage from gradual wear. Work with a roofing contractor who documents damage thoroughly rather than relying on a quick visual estimate alone.
RB Farina Roofing Co has spent more than 10 years replacing storm-damaged roofs across Massachusetts and documenting that damage clearly enough to support an insurance claim, from nor’easter wind and tree damage throughout Arlington and Winchester to hail damage claims following summer thunderstorms across inland communities like Waltham. We provide thorough, photo-documented inspections and written estimates, and we can meet with your adjuster on-site to walk through the scope of damage directly.
We aren’t an insurance company or a public adjuster, and we don’t make coverage decisions, but we handle the roofing side of the claims process clearly and thoroughly so you have what you need to work with your insurer. Every replacement is backed by a workmanship warranty, and for our full range of roofing services beyond insurance replacement, visit our services page.
After storm, hail, or tree damage, you file a claim with your insurance company, which typically sends an adjuster to assess the damage. We can provide documentation and meet with the adjuster to help ensure the full scope of damage is captured, though the coverage decision itself is made by your insurer.
Coverage depends on your specific policy and the cause of damage. Wind, hail, and fallen-tree damage from a documented event are commonly covered, while gradual wear and aging typically aren’t.
We can provide additional photo documentation and a detailed scope of work to support a supplement request or an appeal, though the final decision on coverage and any appeal process itself is between you and your insurer.
When damage is isolated to one section but matching materials aren’t reasonably available, insurers and contractors sometimes agree that full replacement is the more appropriate outcome rather than leaving a visibly mismatched partial repair.
Most standard residential replacements take 1-3 days once the claim is approved and materials are confirmed, similar to any standard roof replacement timeline.
Yes. We can meet with your adjuster on-site to walk through documented damage, though we recommend also communicating directly with your insurance company throughout the process.
If your Massachusetts roof has storm, hail, or tree damage and you’re considering an insurance claim, RB Farina Roofing Co can inspect your roof, document the damage thoroughly, and help you understand the scope of repair or replacement needed.
Schedule a free roof inspection to get started. We serve Boston, Cambridge, Arlington, Waltham, Quincy, and communities throughout Massachusetts, providing the documentation and adjuster coordination that supports your insurance claim process. We’re not an insurance company and can’t guarantee coverage, but we can make sure the roofing side of your claim is documented clearly and thoroughly.
Provide your name, phone number, and any specific service requirements.
